How to Use Charles Schwab ATM Cards Abroad
I still remember the first time a $5 ATM fee hit me while withdrawing cash in Bangkok. That was the…
I still remember the first time a $5 ATM fee hit me while withdrawing cash in Bangkok. That was the start of my search for a truly fee-free way to get money abroad. This guide explains how the Charles Schwab debit card works overseas and the habits that have saved me hundreds of dollars on every trip.
Key Takeaways
- Charles Schwab’s High Yield Investor Checking account reimburses all ATM fees worldwide, with no foreign transaction fees.
- The linked Schwab debit card gives you local currency at the interbank rate.
- Always choose “Local Currency” at the ATM to avoid dynamic currency conversion markups.
- Keep a backup card and set a travel notice to prevent blocks.
- Use the Schwab mobile app to monitor reimbursements and find ATMs.
Why ATM fees add up
When I started traveling internationally, I assumed the occasional $3 fee was just part of the cost. But small charges add up fast when you withdraw cash several times a week, and many banks add a 1-3% foreign transaction surcharge on top of the operator’s fee. A simple $200 withdrawal can easily cost $12 in hidden charges.
I looked for accounts promising truly fee-free withdrawals and found most “no-fee” cards hid markups in dynamic currency conversion or charged monthly fees. Schwab’s stood out: it reimburses the ATM operator fee and charges no foreign transaction fee, so you get the interbank exchange rate.
How the Schwab account works
You need a Schwab High Yield Investor Checking account. The online application takes under ten minutes, with no minimum deposit and no monthly maintenance fees, so you can keep it active just for travel.
You get a Visa debit card linked to your checking balance, and Schwab automatically enrolls you in its Global ATM Fee Reimbursement program. Operator fees are credited back within a few business days, so withdrawals are effectively free. You can open the account on Schwab’s official site: schwab.com.
Setting up your card
Activate the card through the Schwab mobile app or website as soon as it arrives, and set a travel notice in the app so foreign transactions are not flagged as suspicious.
You can also link the checking account to a Schwab brokerage account to sweep excess cash into investments, but keep enough in checking for daily withdrawals.
Using the card abroad
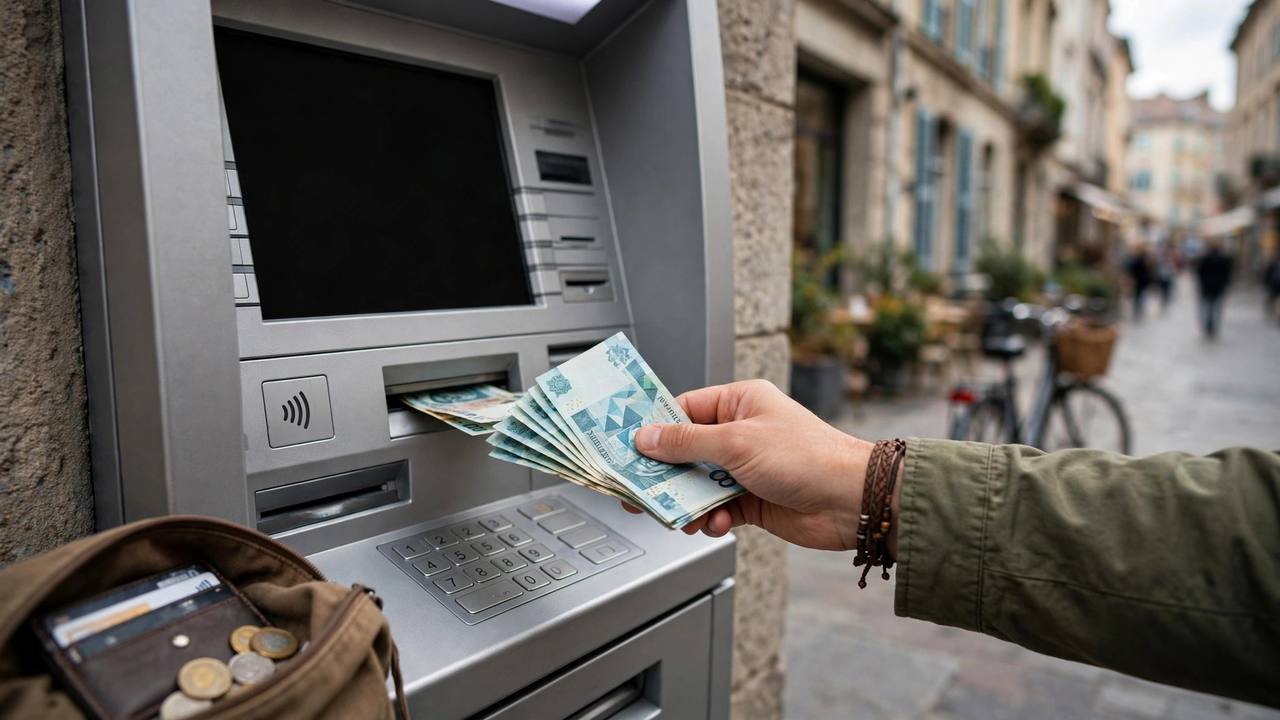
Find an ATM with the Visa or Plus logo; machines attached to major banks are usually the safest and cheapest. Visa’s official ATM locator (visa.com/atmlocator) works well for this. Always withdraw in the local currency and decline dynamic currency conversion, which adds a 3-5% markup.
Insert your card, enter your PIN, and choose your amount. The transaction is converted at the interbank rate with no hidden fees, and the receipt shows the exact amount and rate.
Tracking your reimbursements
Fee reimbursements appear automatically in the app, with a breakdown of each credited fee so you can see exactly what you saved.
If a fee has not been reimbursed after ten business days, contact Schwab support; they resolve it quickly.
What I saved on two trips
On a three-month Southeast Asia backpacking trip, I withdrew cash about three times a week. At $4 per ATM fee plus a 2% foreign surcharge, that would have been roughly $288 in fees. With Schwab, I paid $0.
On a recent European rail trip through Germany, France, and Italy, Eurozone ATM fees averaged 5 euros with a 1.8% surcharge. The savings were even bigger, and the money went to experiences instead of bank charges.
Common pitfalls
Watch for dynamic currency conversion prompts on the ATM screen and always press “Local Currency” or “Without Conversion.” Schwab reimburses operator fees even when they are not part of the Visa network.
Check your card’s expiration date before a long trip and request a replacement early. If the card is lost or stolen, Schwab’s zero-liability protection covers unauthorized transactions once you report it.
Getting the best exchange rates
The Schwab card already gives you the interbank rate. Weekday withdrawals can be slightly better than weekends when markets are less liquid, and withdrawing larger amounts less often reduces the number of ATM visits. Balance that against safety: avoid carrying large sums of cash for long periods.
The Schwab mobile app
The app shows your balance, recent transactions, and pending reimbursements in real time, so you always know what is available.
Its ATM locator finds nearby Visa/Plus machines. Any Visa ATM qualifies for reimbursement, so convenience is all that matters.
Backup plans
No card is infallible. I carry a second debit card from a different bank in a separate location, so a compromised Schwab card never leaves me without funds.
I also keep a small amount of US dollars or euros in a hidden money belt for places where cards are not accepted. For purchases, a rewards credit card is the better tool: see our beginner’s guide to traveling for free using credit card points.
Frequently Asked Questions
Does Charles Schwab charge foreign transaction fees on purchases?
No. The High Yield Investor Checking debit card charges no foreign transaction fees on purchases, and you get the interbank rate on every transaction.
Are there daily withdrawal limits?
Schwab sets a daily ATM withdrawal limit of $5,000 for most accounts, with temporary increases available on request. Individual ATMs may impose lower limits.
How long do reimbursements take?
Typically three to five business days. You can watch pending reimbursements under “Activity” in the app.
Can I use the card for online purchases abroad?
Yes. It works like any debit card online, still with no foreign transaction fees.
What if my card is declined at an ATM overseas?
Check your balance, confirm the ATM accepts Visa or Plus, and make sure you are under the daily limit. If it persists, call Schwab’s international support line (collect calls accepted).
A Charles Schwab debit card is one of the simplest ways to keep more of your travel budget. Zero foreign transaction fees, full ATM fee reimbursement, and the interbank rate make cash effectively free.
Pair it with the right credit card for purchases: our guide to the best no-foreign-transaction-fee credit cards for international travel covers that side, and our $50-a-day budget travel guide covers the rest of your spending.

2 Comments